Golf Betting Strategy: A Framework for Consistent, Data-Led Selections
 Available in US
In 2021 I kept a meticulous log of every golf bet I placed. At the end of the year, I had 312 wagers, a negative ROI of 4.2%, and absolutely no idea why. The selections felt right at the time — good players, reasonable prices, decent form. But “felt right” is not a strategy. It is a narrative dressed up as decision-making.
The following January I scrapped the whole approach and built a repeatable framework: a fixed set of inputs, a consistent process for evaluating them, a staking plan that did not change based on my mood, and a weekly review that forced me to confront what was working and what was not. That year my ROI swung to positive 6.8% on a comparable number of bets. The selections were not dramatically better. The process was.
Golf betting handle on the PGA Tour grew 20% in 2025 — the fourth straight year of double-digit expansion. More money is flowing into these markets than ever, which means the prices are sharper, the edges are thinner, and the punters who rely on gut feel are subsidising those who rely on structure. This guide lays out the framework I use every week: value identification, model inputs, staking discipline, market diversification, and the review cycle that ties it all together.
Why a Repeatable Process Beats One-Off Tips
Pamela Maldonado, the ESPN betting analyst, nailed it when she described golf betting as “a slow-burn panic” and argued that “the sharper approach is building a card with intention and direction.” That distinction — between reacting and directing — is everything in a sport where 156 players tee off and only one lifts the trophy.
A repeatable process beats one-off tips for a structural reason, not a philosophical one. Golf tournaments happen 48 weeks a year across two major professional tours. That is 48 opportunities to refine your method, test your assumptions, and accumulate data on what works. A punter chasing tips resets to zero every Monday. A punter running a process compounds knowledge week on week.
The process does not need to be complex. Mine runs on a spreadsheet and takes about 90 minutes each Tuesday. It has three layers: first, I filter the field down to a shortlist of eight to twelve players using statistical inputs. Second, I compare my probability estimates against the available odds to identify value. Third, I allocate stakes according to a pre-set plan. Every step has a rule. If the rule says pass, I pass — even when the narrative says otherwise.
That rigidity is the point. Golf generates better narratives than almost any sport: the comeback story, the course specialist returning to his favourite venue, the young talent ready to break through. Narratives sell tips. Processes sell discipline. I have never had a narrative-driven bet survive a 48-week season without eventually dragging the P&L into the red. The process bets — boring, data-led, emotionally neutral — are the ones that keep the account healthy.
If you take nothing else from this article, take this: the edge in golf betting is not in finding the winner. It is in finding wagers where the price exceeds the probability often enough to overcome the bookmaker’s margin over the long run. A process ensures you look for that gap in the same way, every week, regardless of the tournament, the field, or how your last five bets landed.
Value Betting in Golf: Finding the Gap Between Price and Probability
Last spring I backed a 70/1 shot who had zero name recognition but whose strokes gained profile matched the course perfectly. He finished tied for eighth. The bet lost — outright winner, not each-way — but the logic was sound. If I could run that tournament a hundred times with the same conditions, his win rate would have exceeded the 1.4% the odds implied. That gap between price and probability is what value means in practice.
The global sports betting market is valued at approximately $162.53 billion in 2025, with projections reaching $575.45 billion by 2035. Inside that ocean of money, the golf corner occupies a niche where value is more accessible than in mainstream sports. Football and basketball markets are hammered by syndicates, algorithms, and millions of casual bets that drive prices toward true probability. Golf markets receive less sophisticated money, which means the odds are less efficient — and the gaps between price and probability are wider.
Value exists when the bookmaker’s implied probability for a player is lower than your estimated true probability. If a sportsbook prices a golfer at 50/1, the implied probability is roughly 2%. If your analysis suggests his true win probability is 3.5%, that is a value bet — not because he will definitely win, but because the return over time from repeatedly making such wagers is positive. You will lose most of these bets individually. But the ones that land pay enough to cover the losses and generate profit, provided your probability estimates are better than random.
The word “better than random” is doing a lot of work in that sentence. It does not mean you need a PhD in statistics. It means you need a structured approach to estimating a player’s chances that accounts for more variables than the bookmaker’s opening line. Form, course fit, field strength, and recent ball-striking data give you four independent lenses. Use all four consistently and you will generate estimates that diverge from the market often enough to find value — not every week, but often enough to matter across a season.
I never chase a single value bet. I am looking for three to five value spots per tournament. Some weeks I find one. Some weeks I find six. The key is that I only bet when the gap is there. Weeks with no identified value get zero bets. That restraint is as important as the analysis itself.
From Fractional Odds to Implied Probability
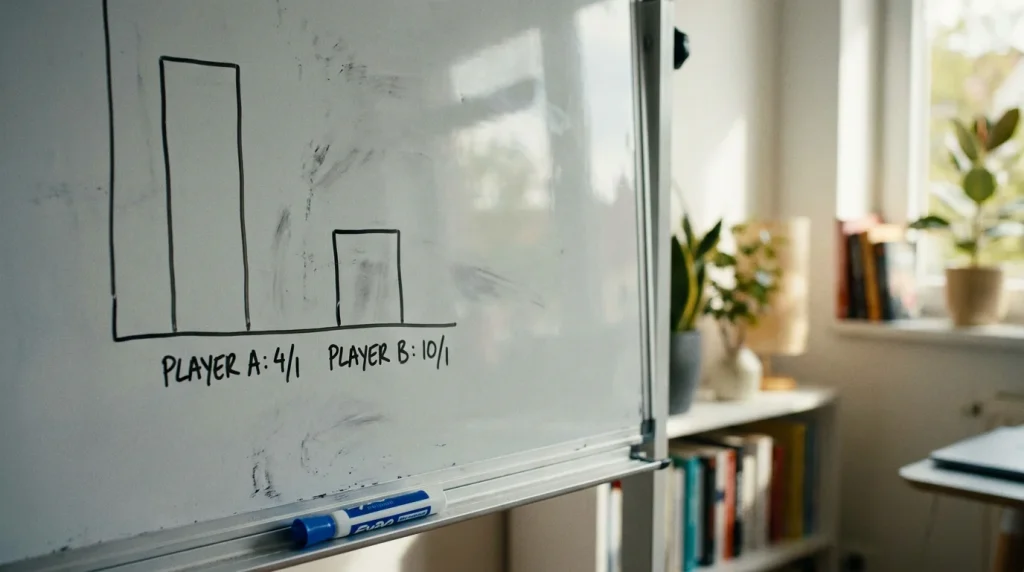
Converting odds to implied probability is the single most useful mechanical skill in golf betting, and it takes thirty seconds to learn. For fractional odds, the formula is: denominator divided by (numerator plus denominator), multiplied by 100. A player at 40/1 has an implied probability of 1 / (40 + 1) = 2.44%. A player at 14/1 has an implied probability of 1 / (14 + 1) = 6.67%.
For decimal odds, it is even simpler: divide 1 by the decimal price and multiply by 100. Decimal 41.0 gives you 2.44%. Decimal 15.0 gives you 6.67%. Same numbers, different format.
The critical step is comparing that implied probability to your own estimate. If you believe a player’s true win probability is 4% and the bookmaker prices him at 40/1 (implied 2.44%), the gap is 1.56 percentage points in your favour. That is a significant edge in a sport where outright win probabilities rarely exceed 10% for even the strongest favourite. You do not need to be right about the exact number. You need to be right about the direction — is the true probability higher or lower than the implied probability? — often enough to show a profit over hundreds of bets.
One caveat: the sum of all implied probabilities in a golf outright market will always exceed 100%. That surplus is the overround — the bookmaker’s built-in margin. A typical golf outright market runs at 120% to 140% overround, meaning you are working against a 20% to 40% house edge embedded in the prices. Your value estimates need to overcome that margin before they generate profit. It is not impossible, but it requires consistent analytical discipline rather than occasional lucky picks.
Key Model Inputs: Form, Course Fit and Field Strength
The three FedEx Cup Playoffs in August 2025 saw betting handle jump 50% year on year, with the Tour Championship more than doubling its action. What drove that surge was not just excitement — it was predictability. Playoff fields are small, the form data is dense, and the model inputs converge. Bettors who use structured inputs perform best when the data is richest, and they know it.
My model runs on three primary inputs: current form, course fit, and field strength. Each one contributes a weighted score, and the combined total produces a ranking that I compare against the bookmaker’s implied ranking. Where the two diverge significantly, I investigate further. Where they align, I move on.
Current form is the most volatile input. A player who has been cutting through fields for three weeks can fade without warning, and a player coming off two missed cuts can suddenly click. The trick is defining “current” in a way that captures genuine performance trends without overreacting to noise. I use a 24-round window — roughly the last six tournaments — because it is long enough to smooth out single-week aberrations but short enough to reflect genuine changes in ball-striking quality.
Course fit is the most underrated input. A links course in windy conditions demands a completely different skill set from a soft parkland track in calm weather. Driving accuracy, approach proximity, scrambling, and putting performance on specific green types all feed into a course-fit profile. I build a statistical snapshot of what the course demands and then compare it to each player’s strokes gained breakdown in those categories. The mismatch between a player’s skill profile and the course demands is often visible in the data long before the market prices it in.
Field strength determines how much weight to give the other two inputs. In a 156-player event where half the field is made up of qualifiers and lower-ranked players, a mid-tier professional with solid form and a good course fit can realistically contend. In a signature event where the top 70 in the world are present, the same player faces stiffer competition at every position on the leaderboard. I use a composite field-strength rating based on world ranking points, and I adjust my probability estimates downward for strong fields and upward for weak ones.
Choosing the Right Form Window
Choosing the right form window is more art than science, but it starts with a principle: shorter windows react faster to real changes in performance; longer windows resist noise better. Neither is inherently superior — they answer different questions.
A 12-round window (roughly three tournaments) is useful for detecting a player who has genuinely improved or declined in the last few weeks. It is also dangerously reactive. One exceptional week inflates the 12-round numbers dramatically, and one terrible week crushes them. I use the 12-round window as a flag, not a verdict. If a player’s 12-round form diverges sharply from his 24-round or 36-round form, that divergence tells me something is changing — but I need to look at the underlying strokes gained data to understand whether the change is real or cosmetic.
A 36-round window (approximately nine tournaments) smooths almost everything. It is the closest thing to a player’s “true level” over a meaningful sample. But it is also slow to pick up on players who are trending upward or falling apart. I treat the 36-round window as the baseline expectation and use the shorter windows to adjust from there.
The specific window matters less than using the same window consistently. If you switch from 12 rounds one week to 36 the next based on what makes a particular pick look better, you are not running a model — you are cherry-picking. Pick a window, stick with it for a full season, and evaluate whether it works in your year-end review. I settled on 24 rounds after testing all three windows across two years of bets, and I have not changed it since.
Staking Plans Compared: Flat, Percentage and Kelly
No staking plan will rescue bad selections, but a bad staking plan can destroy good ones. I learned this the hard way in my second year of serious golf betting, when I had a 7% edge on my selections but ended the season down because I was over-staking long shots and under-staking the bets with the highest expected value.
The three staking approaches worth considering are flat, percentage, and Kelly. Flat staking means every bet is the same size regardless of the odds or perceived edge — one unit per wager, full stop. The US golf betting market was estimated at $3.5 billion in 2023, and a large chunk of that volume comes from recreational punters using something close to flat staking by default. It is simple, it limits catastrophic loss, and it requires no calculation. Its weakness is that it treats a 2% edge bet at 50/1 the same as a 2% edge bet at 8/1, even though the optimal stake for each is different.
Percentage staking sets each bet as a fixed percentage of your current bankroll — typically 1% to 2%. As your bankroll grows, your stakes grow. As it shrinks, your stakes shrink. This protects against drawdowns better than flat staking because your exposure automatically decreases when you are losing. It also accelerates compounding when you are winning. For golf, where losing runs of ten or fifteen bets are routine between cashing, percentage staking provides a buffer that flat staking does not.
Kelly Criterion calculates the theoretically optimal stake based on the size of your edge and the odds offered. The formula is: (edge percentage / odds to 1) times bankroll. In practice, full Kelly leads to wild swings because golf edge estimates are noisy. I use a quarter-Kelly approach — dividing the Kelly-recommended stake by four — which smooths the volatility while still allocating more to higher-edge bets. For a much deeper comparison of all three methods, including worked examples and variance profiles, I have a dedicated piece on golf betting staking plans.
Whichever plan you choose, the non-negotiable rule is consistency. Define the plan before the season starts and follow it for every bet. The moment you deviate — doubling up after a losing week, cutting stakes when confidence drops — you have abandoned the plan and are back to gut-driven staking, which is where bankrolls go to die.
Market Diversification: Spreading Risk Across Bet Types
Most golf bettors are outright addicts. I was one. Every week: pick a player, back him to win, wait four days, lose. The cycle is seductive because the outright market is the most visible, the most discussed, and the one that generates the biggest headlines when someone lands a 66/1 winner. But outright-only betting is portfolio concentration at its worst.
Europe holds 41% of the global sports betting market share, and UK punters have access to a broader range of golf betting markets than almost anyone else in the world. Outrights, each-way, top 5/10/20, matchups, first round leader, make/miss cut, group betting, and in-play propositions — each of these markets prices a different question about a tournament, and the value in each fluctuates independently.
Diversification works in golf betting the same way it works in investing: by reducing the impact of variance on your overall return. An outright bet has roughly a 1% to 5% chance of winning, depending on the player. A top-10 bet might have a 20% to 30% chance. A matchup between two closely ranked players is close to 50/50. Spreading your weekly stake across two or three market types means your P&L is not entirely dependent on the lowest-probability outcome.
My typical tournament card includes one or two each-way outright bets, one matchup, and one top-10 or top-20 wager. The allocation is not equal — outrights get the smallest stake per bet (because the probability is lowest and the variance is highest) and matchups get the largest (because the probability is highest and the variance is lowest). The result is a portfolio of four or five bets that gives me multiple paths to a profitable week rather than a single all-or-nothing shot.
This is not about hedging or reducing excitement. It is about recognising that different markets offer value at different times. Some weeks the outright prices are sharp and the matchup prices are soft. Other weeks the top-10 market is generous while the outrights are overpriced. Diversification lets you put money where the value is, regardless of which market that happens to be.
Weekly Review: Tracking ROI and Adjusting the Process
Every Monday morning I spend 20 minutes reviewing the previous week’s bets. Not the results — the decisions. Did I follow the process? Did the model inputs flag the right players? Were my probability estimates reasonable given the field and conditions? The results matter over 200 bets. They are meaningless over five.
The review covers three dimensions. First, accuracy: how did my shortlisted players actually perform relative to the field? I do not care whether they won; I care whether they finished in the range my estimates predicted. A player I estimated at a 15% chance of a top-10 finish who came in 12th is a near-miss, not a failure. A player I estimated at 3% win probability who came in 40th is noise, not signal.
Second, price quality: were the odds I took reflective of the value I identified? If my model flagged a player as value at 50/1 and the best price I could get was 40/1 after the market moved, I need to note that the execution compromised the edge. Over time, patterns emerge — certain bookmakers consistently offer better prices on certain types of player, and the review is where those patterns become visible.
Third, process adherence: did I stick to the staking plan? Did I make any bets outside the model? Did I add a bet on Saturday evening because a player I liked was storming up the leaderboard? Those off-process bets are the biggest threat to long-term profitability because they feel informed but are actually reactive. My review flags every one, and the year-end totals always confirm the same thing: model-driven bets outperform impulse bets by a wide margin.
I keep all of this in a single spreadsheet with one row per bet and columns for each variable. It takes discipline to maintain, especially after a losing week when the last thing you want to do is log the damage. But the punters who track everything outperform the punters who track nothing, season after season, without exception in my experience.
Golf Betting Strategy: Frequently Asked Questions
How many golf bets should I place per tournament?
Three to five bets per tournament is a sustainable range for most punters running a structured process. That typically breaks down into one or two each-way outrights, one matchup, and one or two positional bets. The exact number depends on how many value spots your model identifies in a given week — some weeks produce five strong candidates, others produce none.
What is a realistic long-term ROI for golf betting?
A consistent, data-driven approach targeting 3% to 8% ROI on level stakes over a full season is realistic for a disciplined punter. Higher returns are possible in shorter bursts, but variance in golf is extreme, and any claimed long-term ROI above 10% should be treated with scepticism unless backed by a large, verified sample of bets.
Should I specialise in one tour or bet across PGA and DP World Tour?
Both approaches have merit. The PGA Tour offers deeper statistical data, which improves model accuracy. The DP World Tour often features softer markets with less efficient pricing, which can mean more value opportunities. I bet across both tours but weight my PGA bets with more confidence because the data inputs are richer and more reliable.
The Process Is the Edge
Golf betting strategy is not about finding a secret formula. It is about building a repeatable process that survives the weeks when nothing lands and compounds the weeks when everything does. Value identification, disciplined staking, market diversification, and honest review — none of these concepts are revolutionary. What makes them powerful is doing all four consistently, every week, for an entire season.
Start the process this week. Run it for twelve tournaments before you judge it. The edge is in the repetition.
Recommend
Published by the Golf Betting Tips team.
